Quick Summary
Adjudicating Officer Amit Kapoor passed the order on November 4, 2026 against Swastika Investmart Limited, a merchant banker. SEBI’s inspection of July 8 to 11, 2025 found missing proof for claims in six SME IPOs and one takeover offer, plus gaps in the firm’s own compliance. The officer imposed a single penalty of ₹10 lakh under Section 15HB, payable within 45 days.
Every IPO offer document carries a promise: the numbers, the claims and the people in it have been checked.
SEBI’s inspectors asked Swastika Investmart Limited to show that checking across six SME IPOs and one takeover offer. Often, there was no paper to show.
The Swastika Investmart SEBI order of November 4, 2026 records what they found, what the firm said, and why the penalty is ₹10 lakh.
Swastika Investmart Inspection Timeline: July 2025 To The Final Order
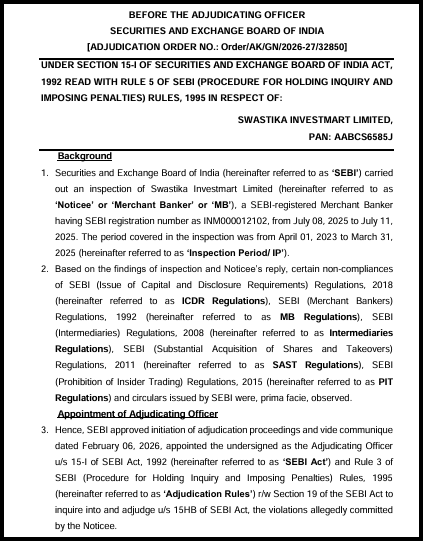
SEBI inspected the firm from July 8 to July 11, 2025. The inspection covered April 1, 2023 to March 31, 2025.
Based on the findings and the firm’s reply, SEBI saw prima facie non-compliance with six sets of rules.
They were the ICDR Regulations, MB Regulations, Intermediaries Regulations, SAST Regulations, PIT Regulations, and SEBI circulars.
The case then moved as shown below:
| Date | Step |
|---|---|
| July 8 to 11, 2025 | SEBI inspection |
| February 6, 2026 | Amit Kapoor appointed Adjudicating Officer |
| March 18, 2026 | Show cause notice issued (sent March 20, 2026) |
| April 2, 2026 | Firm’s reply |
| April 29, 2026 | Hearing notice |
| May 12, 2026 | Personal hearing, with authorised representatives repeating the reply |
| November 4, 2026 | Order passed in Mumbai |
The firm acknowledged receipt of the notice by email on March 20, 2026. In its reply, it said it had already strengthened its processes.
IPOs And Takeover Offer SEBI Reviewed In The Inspection
The inspection looked at six SME IPOs and the takeover offer for Shalimar Paints Limited.
The table below shows the main issues for each one:
| Offer | Type | Main issues found |
|---|---|---|
| Aditya Ultra Steel Limited | SME IPO | Unsupported director credentials, untested fund estimates, guarantee and customer risk, undisclosed NCLT petition |
| TBI Corn Limited | SME IPO | Unsupported credentials, no defaulter database check, single vendor quote, double counted costs, no site visit report |
| Service Care Limited | SME IPO | No site visit proof, no due diligence file, “23 years” claim, advisory fee disclosure |
| Sai Swami Metals and Alloys Limited | SME IPO | No site visit proof, no due diligence file, unsupported dealer and retail claims |
| Resourceful Automobile Limited | SME IPO | Invoice mismatch, missing debt-use certificate, unsupported business claims |
| United Heat Transfer Limited | SME IPO | Unsigned site report, no defaulter check, conflicting litigation and revenue figures |
| Shalimar Paints Limited | Takeover offer | Unsupported claims, no defaulter check, SEBI warning letter not disclosed |
Each theme is covered in the sections that follow.
What Does A Merchant Banker’s Due Diligence Certificate Cover?
Before the issues, here is the standard the officer applied.
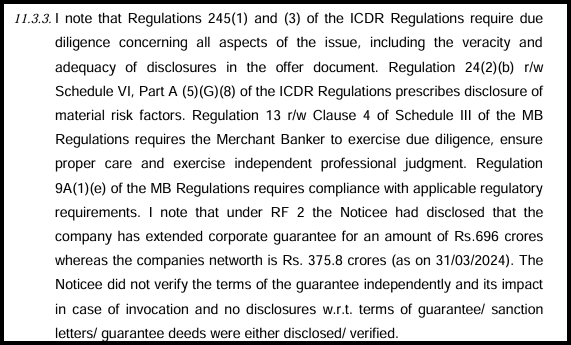
Regulation 245(1) and (3) of the ICDR Regulations require due diligence on all aspects of an issue, including the veracity and adequacy of disclosures in the offer document.
Regulation 13 of the MB Regulations, read with Schedule III, asks a merchant banker to show integrity, due diligence and independent professional judgment. It must also ensure information is true, adequate, and not misleading.
If you want to see where this fits in a public issue, our IPO process in India guide walks through the steps from the draft document to listing.
The officer repeatedly asked a simple question: where is the record that shows the check was done?
Unverified Director Qualifications In IPO Offer Documents
Offer documents describe the people running the company. The inspection asked for the papers behind those descriptions.
- Aditya Ultra Steel. The offer document listed five directors and key managerial personnel as qualified and experienced. The firm could not provide supporting certificates.
- TBI Corn. The same gap appeared for the directors and KMPs listed in its offer document.
- Resourceful Automobile. For three directors, the firm held plain-paper declarations that educational certificates were missing. It had no copies of FIRs and no experience certificates.
- Shalimar Paints takeover. Claims about the qualifications of directors and promoters of both acquirer and target rested on résumés from the company.
The firm’s defence was that it relied on résumés and confirmations from the individuals and company. The officer held that the firm failed to verify the claims and found violations in each case.
Working Capital, Capex And Guarantee Figures SEBI Questioned
The “objects of the issue” tell investors where IPO money will go. The officer looked at how those figures were backed up.
- Working capital estimates. Aditya Ultra Steel’s estimate was ₹14.35 crore, and TBI Corn’s was ₹17 crore. The firm had no supporting calculations and no CA certificate, and relied on management estimates.
- A single quote. Aditya’s capex of ₹15.35 crore for solar power rested on one vendor’s quotation, with no proof of the advance paid. TBI Corn’s machinery also came from one vendor.
- Double counting. For TBI Corn, transport and taxes were already inside the machinery price but were shown again. The firm admitted this was unintentional.
- A guarantee beyond net worth. Aditya’s risk factor 2 disclosed a corporate guarantee of ₹696 crore, while net worth was ₹375.8 crore as on March 31, 2024. The firm did not verify the guarantee terms or what invocation would mean.
- Customer concentration. Risk factor 5 said the top ten customers gave about 95% of revenue. The single largest customer gave nearly 56%, which was not a separate risk factor.
- Debt repayment and an invoice. For Resourceful Automobile, the firm had no CA certificate on use of earlier loans and no lender NOCs. The vendor’s invoice also did not match the GST portal records for the proprietor’s name.
On the CA point, the firm argued that Chartered Accountants cannot vouch for future projections.
The officer replied that certifying an estimated working capital need is not the same as assuring a projection, so the argument was not tenable.
Missing Site Visit Reports And Due Diligence Records
A site visit and a due diligence certificate are the two steps that show a merchant banker looked beyond the paperwork.
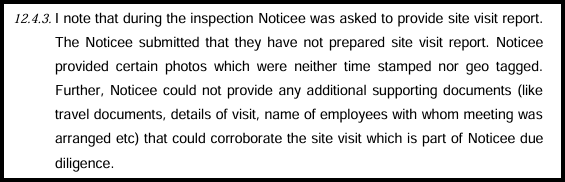
- No site visit reports. For TBI Corn, the firm had no report. Photos were neither time-stamped nor geo-tagged, and it had no travel records or names of the people met.
- Same story elsewhere. For Service Care, Sai Swami Metals and Alloys and Resourceful Automobile, the firm said in a letter of July 8, 2025, that it had no supporting documents for the site visit.
- A report with a date clash. For United Heat Transfer, the site report was unsigned and dated April 11, 2024, while the photograph was dated April 14, 2024. The firm later called its own date a clerical error.
- Due diligence files. For Service Care, Sai Swami and Resourceful, the firm wrote that it had no documents showing what it obtained to prepare the certificate. The officer called the absence material, since the certificate says the offer document was examined and verified.
The officer said a site visit counts as due diligence only when the firm can show when it happened, who took part, what was examined, and what was concluded.
The firm also said discussions with management, auditors and the legal advisor took place. The officer held that general references to emails and a data room, without identified records, do not show the basis for the certificate.
Also Read: Why MCS Share Transfer Agent Was Fined For Weak Record-Keeping
Wilful Defaulter And Litigation Checks In SME IPOs
Offer documents tell investors whether directors face cases or appear on defaulter lists.
Here, the firm leaned on advisors’ reports:
- Aditya’s NCLT petition. Company Petition CP/19(AHM) of 2022 in the NCLT Ahmedabad concerned alleged default in repaying deposits of ₹48.13 lakh with interest. It was not shown under contingent liabilities and the interest was not quantified.
- No database subscription. For TBI Corn, the firm stated that no director was on the RBI wilful defaulter list or a fugitive economic offender. It had no subscription to the Watchout Investors database to check.
- Repeated for others. The same lack of independent checks was found for United Heat Transfer and the Shalimar Paints takeover.
The firm said it relied on legal reports and has since subscribed to the database. The officer held that a legal report may support due diligence but does not replace the firm’s independent obligation.
The officer also noted that subscribing after the inspection is a corrective step, not proof that disclosures were verified when made.
SME offers have drawn SEBI’s attention before, as in the Synoptics IPO case.
Contradictions And Unsupported Claims In Offer Documents
Some findings did not need outside records. The documents contradicted themselves, or claims had no backing.
- Service Care’s age. The firm’s own offer document described more than 23 years of experience, while the company was incorporated on May 13, 2011, about 12 years before the filing. The firm called it a clerical error.
- An advisory fee. Service Care paid Neomile Corporate Advisory Limited ₹2,47,86,000, more than 10% of the issue size. The offer document did not disclose this, as the firm’s other offer documents did.
- Sai Swami’s reach. The offer document claimed over 150 dealers in Gujarat, Madhya Pradesh and Maharashtra and about 6 distributors with over 200 stockists and retailers. It also named retail chains and e-commerce platforms. The firm had no supporting documents.
- United Heat Transfer’s cases. Page 15 of the DRHP said no litigation was pending, while page 21 listed 11 cases against the company and five against group companies. State-wise revenue figures for Maharashtra were also inaccurate and did not match across pages.
- Resourceful’s claims. The offer document spoke of partnerships with leading motorcycle manufacturers and eight permanent employees. The firm had salary slips for six, and the rent agreements were only notarised on ₹50 or ₹100 stamp paper, with some unsigned by both parties.
For Resourceful, the officer rejected the clerical error explanation. The order notes the industry data was not from an authentic source and the firm had not independently verified it.
Shalimar Paints Takeover Offer: SEBI Warning Letter Not Disclosed
The Shalimar Paints takeover offer raised a different point. It was about what the Letter of Offer left out.
- Unsupported brand claim. The draft offer said Hella Infra operates under the brand Infra.Market. The firm had nothing to back it up.
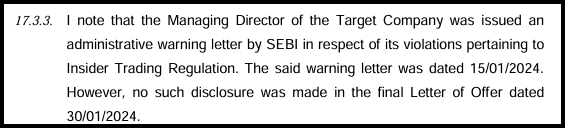
- The warning letter. SEBI had issued an administrative warning letter on January 15, 2024, to the target company’s Managing Director for insider trading regulation violations. The final Letter of Offer of January 30, 2024, did not mention it.
- The firm’s view. It argued the warning was advisory and non-punitive, so it was not material.
The officer said the advisory nature was not decisive. The warning concerned a securities-law matter and was known before the final letter, so the firm had to assess materiality and show that it did.
Compliance Lapses At The Firm: Investor Charters, PIT Code And More
The inspection also looked at how the firm ran its own compliance. These findings were not about any one offer.
- Investor charters and complaints data. Charters for rights issues, QIPs, SME IPOs, FPOs, OFS and SAST were not on its website. Complaints data required by the circular of November 23, 2021 was also missing, and the officer noted an initial misstatement in the firm’s reply and belated compliance.
- Incomplete track record. Details such as the basis of issue price, trading status, and issuer financials were not fully shown for the last three financial years.
- A 20-day gap. The firm had no Compliance Officer from May 10 to May 30, 2023. It said the old officer resigned and a new one was appointed on May 9, 2023, but gave no documents, and its records showed the designation change on May 31, 2023.
- One email for many uses. The email ID meant for regulatory communications was also used for investor grievances and for communication with financial institutions.
- No insider trading framework. There was no Code of Conduct under Regulation 9(1) read with Schedule C of the PIT Regulations and no Compliance Officer under Regulation 9(3). The Structured Digital Database software only began on October 23, 2024, and the designated persons list was incomplete and left out KMPs.
- No email firewall. There was no firewall or authentication check for emails from the merchant banking division to other divisions. The firm said the HR team had temporarily shared its office space.
The officer treated the steps the firm took after the inspection, such as adopting the Code of Conduct and adding people to the database, as corrective measures.
They did not undo the lapses in the inspection period.
Also Read: Som Distilleries SEBI Order
Understanding SEBI’s ₹10 Lakh Penalty on Swastika Investmart
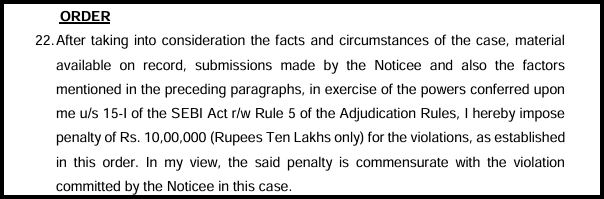
Section 15HB sets a penalty of not less than ₹1 lakh and up to ₹1 crore where no separate penalty is provided.
The officer applied the Section 15J factors:
- No quantified gain. No figures were available for disproportionate gain or unfair advantage.
- No ascertainable loss. The exact monetary loss to investors could not be worked out.
- A past penalty. The record showed SEBI had imposed a penalty on the firm in the past. The order gives no further details.
The officer imposed a single penalty of ₹10 lakh for all the violations found.
Is Swastika Investmart Limited SEBI Registered Or Not?
Yes. The order describes Swastika Investmart Limited as a SEBI-registered Merchant Banker with registration number INM000012102.
SEBI’s inspection of the firm ran from July 8 to 11, 2025. The order notes that, as a SEBI-registered intermediary, the firm must comply with the applicable circulars, rules and regulations.
Penalty Payment Deadline And Recovery Under Section 28A
The firm must pay within 45 days of receiving the order. Payment is online on the SEBI website under Enforcement, Orders, Orders of AO, Pay Now.
For payment problems, the order lists [email protected].
If it is not paid, SEBI may start recovery under Section 28A of the SEBI Act, with interest. That can include attachment and sale of movable and immovable property.
What Investors Should Check Before Applying To An SME IPO?
The order does not say any investor lost money because of these lapses. It does show what to look for in offer documents.
- Check the risk factors. The guarantee figure and customer concentration were there for readers to see, which makes them worth reading.
- Compare pages. Contradictions between sections of the same document are a warning sign.
- Read about the people. Directors’ backgrounds are part of the disclosure, so see what is said about their cases and credentials.
- Note the lead manager. Offer documents name the merchant banker responsible for the checks.
If you think an issuer or intermediary broke the rules, you can file a SEBI SCORES complaint and follow it online.
Conclusion
The Swastika Investmart SEBI order shows how much weight SEBI puts on the paper trail behind an offer document.
Across seven offers, the same gap kept appearing: claims were made, but the proof was not on file.
The ₹10 lakh penalty is modest, but the findings spell out what an independent check should look like.
Report. Recover. Stay Fraud Free.
Adjudicating Officer Amit Kapoor passed it on November 4, 2026 in Mumbai, under Section 15-I of the SEBI Act. A single penalty of ₹10,00,000 under Section 15HB of the SEBI Act, for all violations found. Six SME IPOs (Aditya Ultra Steel, TBI Corn, Service Care, Sai Swami Metals and Alloys, Resourceful Automobile, United Heat Transfer) and the Shalimar Paints takeover offer. The inspection ran from July 8 to 11, 2025 and covered April 1, 2023 to March 31, 2025. The officer treated steps taken after the inspection as corrective only. They did not cure the lapses in the inspection period. The officer said a legal report can form part of due diligence, but it does not replace the firm's own independent checks of litigation and defaulter status. No. The order says exact monetary loss to investors could not be ascertained, and no gain was quantifiable. It has 45 days from receipt of the order, after which SEBI may recover the amount with interest.Frequently Asked Questions



 Add us as a preferred source on Google »