Quick Summary
Legitimate advisors and fund managers never ask you to wire money to a personal bank account.
Funds should only move to an account in the name of a verified, registered entity.
Large scale schemes have collected thousands of crores before their structure was ever exposed.
This checklist covers exactly what to verify before you send a single transfer.
One scheme collected Rs 3,000 crore from investors before its structure finally came apart.
Every rupee moved the same way countless smaller scams do, through a bank transfer to an entity that looked legitimate.
The size of the number changes, the pattern rarely does.
Before you wire money to any advisor or fund manager, run this checklist first.
The Pre Transfer Checklist
Confirm every point below before any money leaves your account.
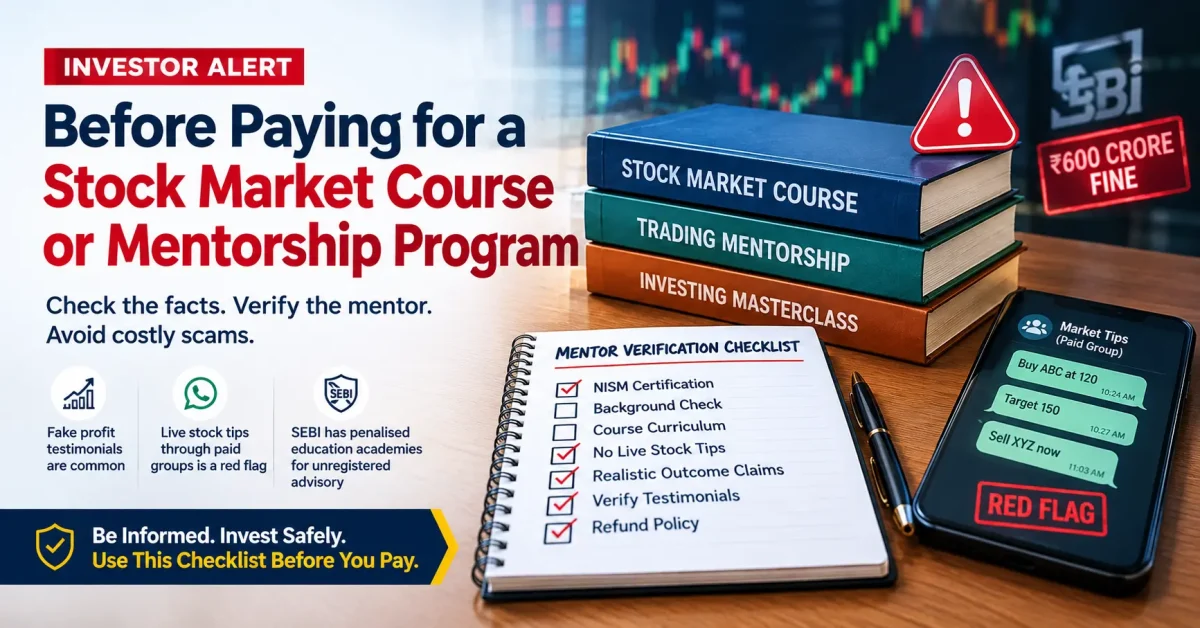
- Account name match: The bank account name must exactly match the registered entity, never an individual’s personal account.
- SEBI registration check: Verify the entity’s registration number directly on SEBI’s website before proceeding.
- Written agreement first: A formal, signed agreement should exist before any transfer, not after.
- No pressure to rush: Genuine fund managers don’t create artificial urgency around your decision timeline.
- Independent verification: Search the entity’s name alongside SEBI orders, complaints, or investigations.
- Start small if uncertain: A first transfer should be modest and traceable, never your full intended commitment.
- Keep every record: Save agreements, chats, and transfer receipts from the very first transaction.
Verifying Before You Transfer, Step by Step
1. Confirm registration: search the entity’s SEBI number directly on SEBI’s official Intermediaries page.
2. Match the bank account name: against the registered entity name, not the individual pitching you.
3. Search for enforcement history: look for the entity’s name alongside terms like SEBI order, complaint, or fraud.
4. Request the agreement first: read and sign a formal document before any money changes hands.
5. Send a small test transfer: if still uncertain, and confirm normal processing before committing further funds.
Why the Account Name Matters So Much
A genuine registered entity operates through accounts in its own verified name, not an employee’s personal account.
Funds routed to a personal account are far harder to trace and recover if something goes wrong.
This single check has exposed more fraudulent pitches than almost any other verification step.
How Large Schemes Stay Hidden for So Long
One case involved a scheme collecting Rs 3,000 crore, where impersonation and evasive responses to SEBI delayed exposure, detailed in how a Rs 3000 crore Ponzi scheme was exposed.
Even a video call arranged to verify management can be staged with the wrong person present.
This is why independent verification matters more than any single conversation, however convincing.
Small Pitch vs Large Scheme: The Pattern Repeats
| Element | Small Scale Pitch | Large Exposed Scheme |
| Entry point | Personal contact or referral | Broader marketing, apparent legitimacy |
| Fund routing | Personal or unverified account | Layered entities, shell structures |
| Verification difficulty | Easy to check quickly | Harder, requires deeper digging |
| Underlying tactic | Trust exploitation, same core pattern | Trust exploitation, same core pattern |
Bottom Line
A verified account name and a checked registration number are your two fastest safeguards before any transfer.
Explore the full checklist series and Fraud Free‘s broader resources for every entity type.
If a registered entity is disputing your funds, you can try SMART ODR conciliation as a faster resolution route.
Report. Recover. Stay Fraud Free.
Frequently Asked Questions
No. Funds should only move to an account held in the name of the registered entity itself. A request to wire money to a personal account is a significant warning sign of a fraudulent pitch.
Check their SEBI registration number directly on SEBI's website, confirm the entity name matches the bank account, and search for any past enforcement actions or investor complaints.
Yes. Some fraudulent schemes have collected thousands of crores before exposure, using impersonation and evasive tactics to delay scrutiny. Scale and apparent sophistication are not proof of legitimacy.
Verify independently beyond the call itself. There are documented cases where the wrong person appeared on a verification call, impersonating a company's actual leadership.
Keep it modest and traceable rather than committing your full intended amount immediately. This limits potential losses while you continue verifying the entity's legitimacy over time.
Yes. Whether the amount is modest or runs into crores, the core mechanism is the same: trust exploitation through a legitimate seeming entity. Scale changes, the underlying tactic usually doesn't.

 Add us as a preferred source on Google »