Quick Summary
Karz Mukt Bharat Abhiyan, also called Karz Mukti Abhiyan, is a name used by debt relief campaigns that tell struggling borrowers their loans can be wiped out. It is not a government scheme. In Punjab, borrowers paid ₹50 to ₹500 to join such campaigns, received membership receipts they thought were waiver certificates, and stopped paying EMIs. The RBI warned on 11 December 2023 and again on 4 May 2026 that paid “debt waiver certificates” are false and misleading and don’t change what you owe.
When EMIs pile up and recovery calls start, any promise of relief feels like a lifeline. Then someone at a rally or on Facebook says you can be free of your loans just by joining a campaign.
That’s the promise behind Karz Mukt Bharat Abhiyan and campaigns with similar names, and it has left many borrowers worse off than before.
Below, we explain what these campaigns claim, what happened when borrowers believed them, and the real options you have when repayments get hard.
If someone has already taken money from you on this promise and you want to report financial fraud in India, the steps are near the end.
What Is Karz Mukt Bharat Abhiyan?
The name translates to “Debt Free India Campaign,” and that’s exactly the feeling it sells.
Here’s how these campaigns present themselves.
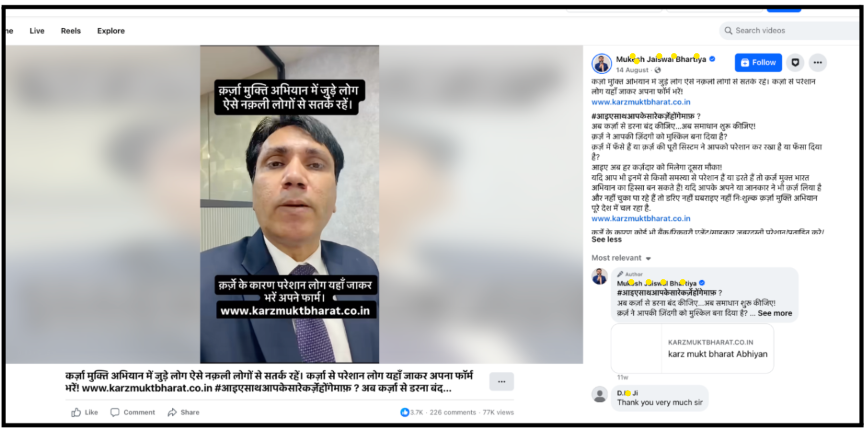
Social media posts using the name speak directly to people who can’t repay bank loans, microfinance loans, or private moneylenders.
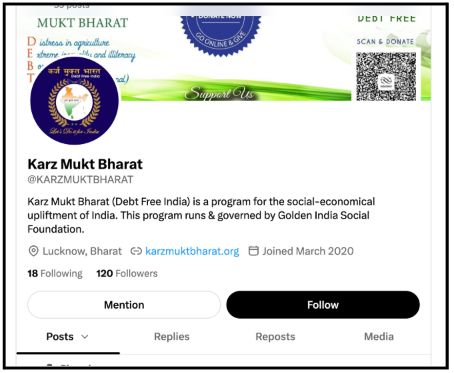
They promise a “second chance,” invite borrowers to fill a form on a website, and offer help against harassment by recovery agents.
On the ground, similar campaigns run under names like Karz Mukti Abhiyan.
They hold rallies, enrol members and, in some places, have used political party names and symbols to look more official.
Is Karz Mukt Bharat Abhiyan Real or Fake?
Karz Mukt Bharat Abhiyan is not a government scheme, and it has no RBI approval to waive loans.
Only your lender can change what you owe, and any genuine waiver or settlement comes in writing from that bank, NBFC, or MFI.
Joining a campaign, filling its form or paying its fee doesn’t reduce your loan by a single rupee.
A membership card or receipt is just that: proof that you joined a group.
What Is a Karz Mukt Bharat Loan Waiver Scam?
Not everyone who uses the campaign’s name is out to cheat you.
The trouble starts when someone asks for money in return for making your loan disappear.
The pattern is simple. Borrowers are told that once they pay a joining or registration fee, their loans will be waived and they can stop paying EMIs.
Some are handed receipts or certificates that look official.
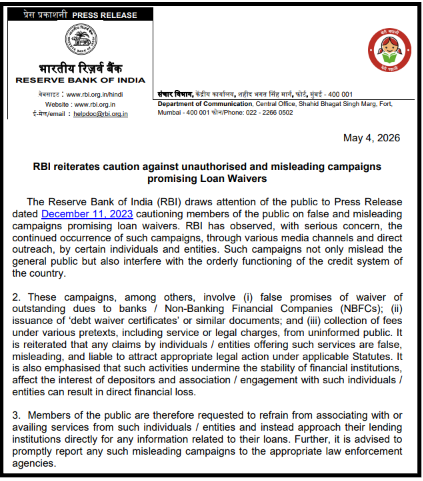
The RBI has described exactly this. It said some entities charge a “service or legal fee” for issuing “debt waiver certificates” without any authority, and that these claims are false and misleading and may attract legal action.
Also Read: A reviewer alleged that nearly 40% of profitable trades went towards fees and that stop-loss orders repeatedly failed, adding to the concerns surrounding Delta Exchange.
What Happened in Punjab With Karz Mukti Abhiyan?
The clearest picture of how these campaigns affect real borrowers comes from Punjab.
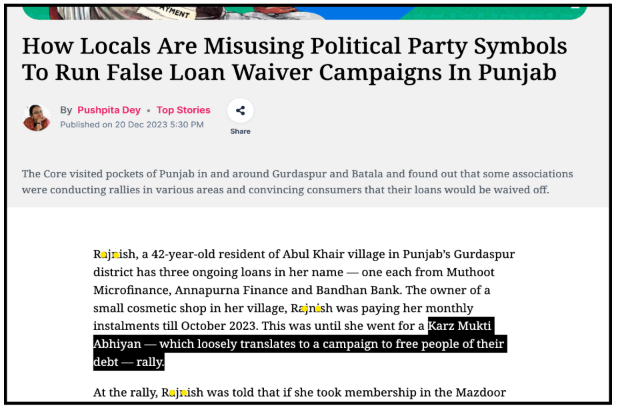
In December 2023, The Core investigated campaigns around Gurdaspur and Batala.
Local groups held rallies under names like Karz Mukti Abhiyan and Mazdoor Mukti Morcha, sometimes using political party logos.
They approached borrowers with microfinance and private bank loans, many of them women and farmers.
Borrowers paid a joining fee of about ₹50 to ₹500.
Two borrowers in Gurdaspur paid ₹100 each, received membership receipts, and stopped paying their EMIs, believing their dues would be waived.
The receipts said nothing about any loan waiver. They only recorded membership of the group.
Meanwhile, a microfinance lender told The Core that nearly 60 to 70% of its borrowers in Gurdaspur hadn’t repaid in the previous two months.
To be fair to the groups involved, a leader quoted by The Core said they were not asking people to stop paying, and a political party whose name was being used said it never tells borrowers not to repay.
Also Read: Mudra Loan Fraud, where fake approval letters ask small business owners for a fee before a loan that never comes.
What Happens If You Stop Paying EMIs on a Waiver Promise?
This is the part most borrowers only discover later. Here’s what stopping payments actually does, whatever a campaign may have told you.
- Your loan stays fully due. Interest and late charges keep adding up on top.
- Missed EMIs are reported to credit bureaus, which lowers your credit score.
- A lower score makes future loans harder, even small ones from banks and MFIs.
- The lender can start recovery under the terms of your loan agreement.
- You also lose whatever fee you paid to join the campaign.
Joining a campaign doesn’t protect you from any of this. Only a written decision from your own lender can change your loan terms.
Real Options When You Can’t Repay a Loan
If repayments have become impossible, you still have genuine options, and none of them needs a campaign fee.
Start with whichever fits your situation.
Talk to Your Lender Directly
Visit your bank, NBFC, or MFI branch and explain your situation honestly.
Ask in writing about restructuring, a longer tenure, or a one-time settlement.
A settlement can close a loan for less than you owe, but your credit report may show it as “settled” rather than “closed.”
Ask the lender to explain this before you sign.
If Recovery Agents Harass You
RBI rules don’t allow lenders or their agents to threaten, abuse, or call you at odd hours.
Complain to the lender in writing first.
If you get no reply within 30 days, or the reply doesn’t solve it, you can complain to the RBI Ombudsman. In case of threats, go to the police.
What to Do If You Paid a Karz Mukt Bharat Campaign?
If you’ve already paid a fee or shared your documents on a waiver promise, these steps help limit the damage.
- Restart your EMIs or speak to your lender right away, before more missed payments hit your credit report.
- Keep the receipt, certificate, and any messages showing what you were promised and what you paid.
- Report it on cybercrime portal if you paid online, or at your local police station if you paid in cash.
Our walkthrough on how to file a cyber crime complaint shows what details to include so your complaint isn’t sent back for missing information.
Paid a fee to make your loan disappear, and now the lender is calling again?
Tell us what you paid, to whom, and what you were promised. We’ll help you work out your next step with both the campaign and your lender. Register with us for a free consultation.
Disclaimer: This article is based on RBI press releases and a published news investigation. It describes how loan waiver campaigns using these names have operated and does not accuse any specific organisation, political party or individual of wrongdoing.
Conclusion
Karz Mukt Bharat Abhiyan sells a hope that every struggling borrower wants to believe. But no campaign, form or fee can cancel a loan that a bank or MFI gave you.
In Punjab, borrowers paid to join, stopped their EMIs, and were left with membership receipts and growing dues.
The RBI has now warned twice that paid “waiver certificates” are false and misleading.
If repayments are hard, go to your lender, not a campaign. And if someone has taken money from you on a waiver promise, keep your receipts and report it.
Report. Recover. Stay Fraud Free.
Frequently Asked Questions
No. It is not a government scheme and has no RBI approval to waive loans. Only your own bank, NBFC or MFI can change what you owe, and it does so in writing.
No. Joining, filling a form or paying a fee does not waive any loan. The RBI has said paid "debt waiver certificates" are false and misleading.
On 11 December 2023 and again on 4 May 2026, the RBI warned that entities charging fees for "debt waiver certificates" have no authority, and that dealing with them can cause financial loss.
Your loan stays due with interest and late charges, missed EMIs are reported to credit bureaus, and your credit score falls. The lender can also start recovery under your loan agreement.
Complain in writing to your lender first. If it is not resolved within 30 days, file a complaint with the RBI Ombudsman, and go to the police in case of threats.

 Add us as a preferred source on Google »