Quick Summary
Upasana Mondal is an individual SEBI registered investment adviser, INA200011684, who practises as DreamBluePrintz from Goa. Registered since 12 September 2018, she lists a fixed fee financial plan at ₹22,000 and a ₹12,000 renewal. Her monthly table shows one complaint, received in May 2026 and resolved in June 2026, with none pending. The data starts only in September 2025. The website shows no terms or privacy policy. We found no SEBI order against her as of 20 October 2026, which is not a clean certificate.
You may be looking for a fee only financial planner who does not earn commissions, and a plan with a clear price is a good place to start. This blog looks at Upasana Mondal Investment Adviser through her own disclosures.
A fixed fee still needs a close read, because it is the scope, the terms and the record behind the fee that tell you what you are buying.
We cover the registration, the credentials she lists, the fee, the complaint tables and the missing policies, then turn the gaps into questions you can send in writing.
Who Is Upasana Mondal and What Is DreamBluePrintz?
Upasana Mondal is the founder of DreamBluePrintz, which her website describes as a fixed fee financial planning practice.
She is registered with SEBI as an individual investment adviser and works from Benaulim, Goa.
She describes herself as an independent adviser who does not earn commissions from financial products.
Additionally, she says that approach lets her give unbiased advice.
Background She Lists
The website says she has 18 years of work experience and has prepared financial plans since 2011, for clients in India and the US.
It says she previously worked with Canara HSBC Life Insurance and Ameriprise.
These are statements from her own website.
Ask for the dates and roles if they matter to your decision.
Credentials
She lists a Certified Financial Planner certification awarded by the Financial Planning Standards Board India, a Fellowship of the Insurance Institute of India and an MBA.
She is also a director on the board of the Association of Registered Investment Advisors and a member of Fee Only India.
Credentials of this kind can usually be checked with the body that issues them.
Ask for the certificate details and do a quick check, which takes a few minutes.
The Services
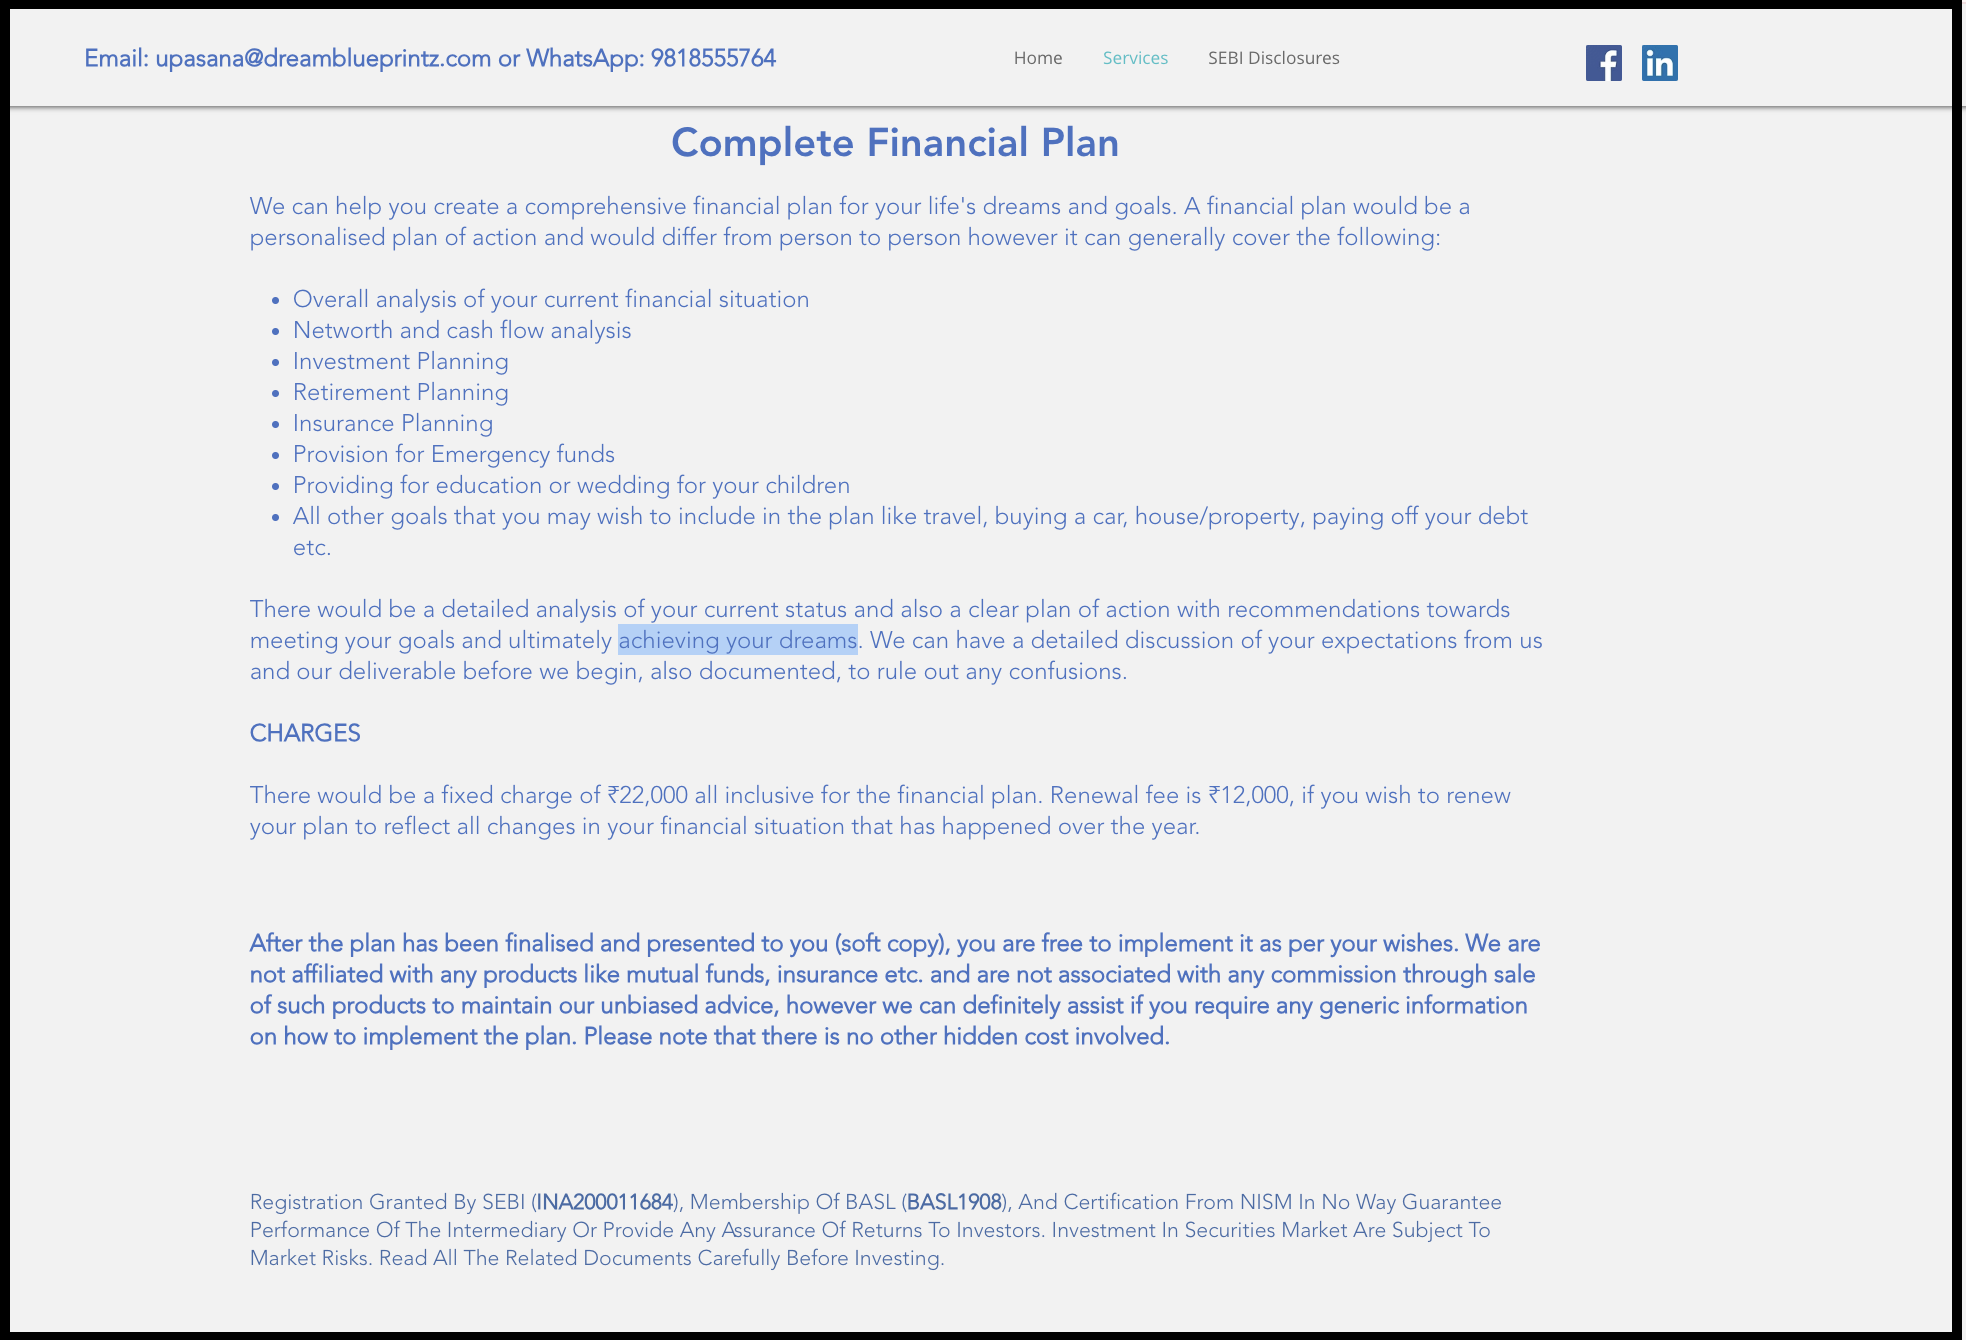
The services cover comprehensive financial planning built on your situation, goals and expectations.
They include net worth and cash flow analysis, investment, retirement, insurance and emergency fund planning.
Planning for children’s education and weddings is also listed, along with goals such as travel, a car, property or debt repayment.
The output is a set of recommendations and a documented action plan.
Help with Implementation
The site says clients can carry out the plan themselves, and that she can give general guidance on implementation.
It does not say whether ongoing advice or portfolio reviews are included.
Ask whether any help after the plan is delivered is included or billed separately.
Is Upasana Mondal a SEBI Registered Investment Adviser?
The research shows Upasana Mondal listed as a registered investment adviser.
Each point below is what the listing shows, and you should confirm it yourself before relying on this page.
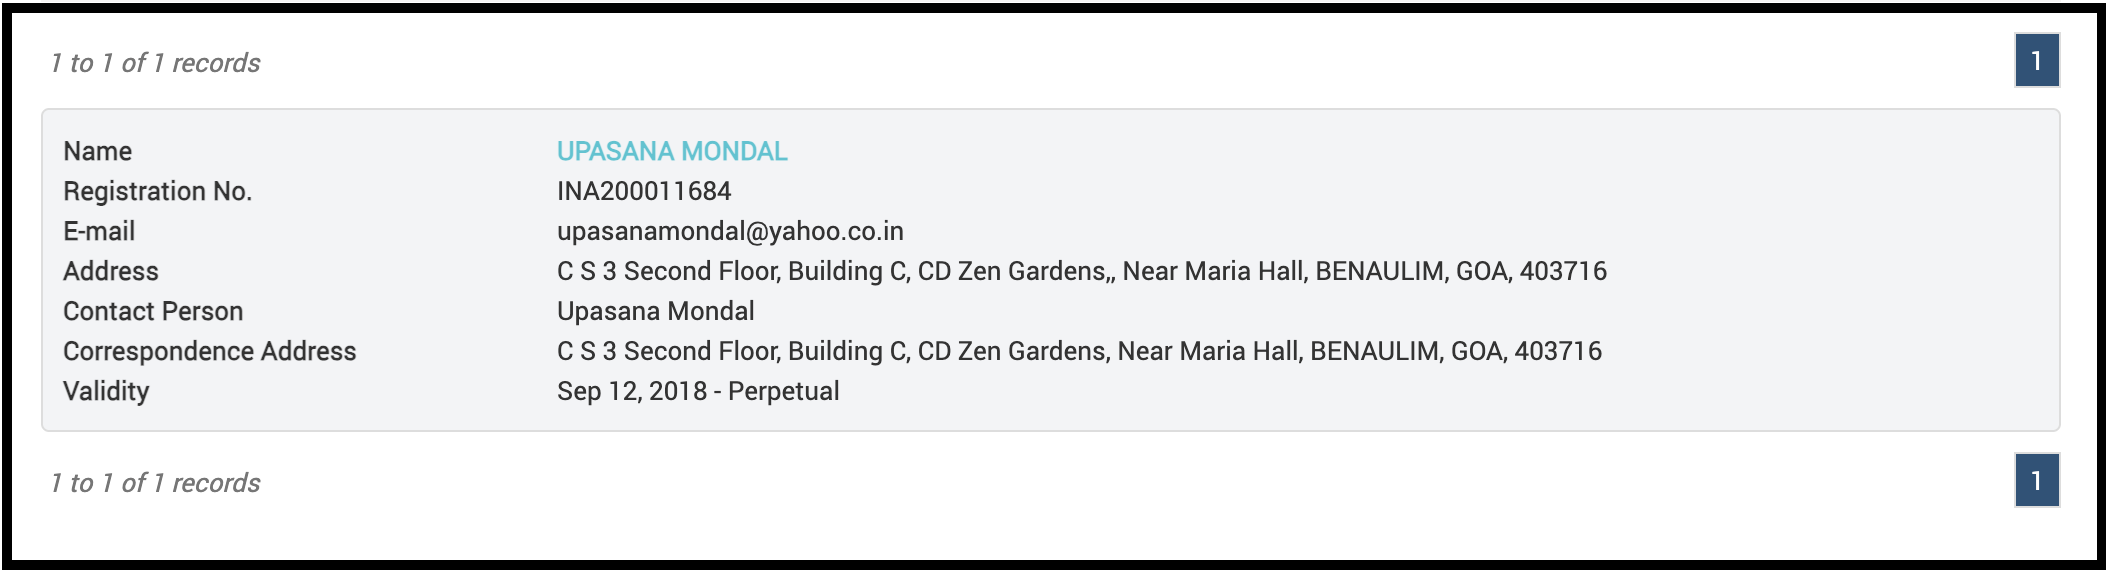
- Registration number is INA200011684. The INA prefix marks an investment adviser, unlike INH for a research analyst or INP for a portfolio manager.
- Registered name is Upasana Mondal, an individual. The brand name DreamBluePrintz is her practice name, so check that payments and the agreement name the registered person.
- Validity runs from 12 September 2018 and is listed as perpetual. That makes the registration about eight years old.
- Address is C S 3, Second Floor, Building C, CD Zen Gardens, Near Maria Hall, Benaulim, Goa 403716, with the same correspondence address. The email on the listing is a Yahoo address.
You can verify this in a few minutes.
A SEBI investment adviser registration verify lets you enter INA200011684, compare the name and category, and see whether the registration is active.
A SEBI registration number search on the regulator’s own pages does the same job.
Do it before you pay anyone, and save a dated screenshot.
Registration shows that a person may give investment advice. It does not describe the quality of advice or the fee.
Upasana Mondal Investment Adviser Fees and Renewal Charges
The website shows its prices openly, which is a point in her favour. There are two charges.
|
Service |
Charge |
|
Comprehensive financial plan |
₹22,000, described as all inclusive |
| Renewal of the plan |
₹12,000 |
The renewal applies if you want the plan updated for changes in your situation over the year. The website says there are no hidden costs.
How the Fees Sit Against the Cap
SEBI caps fixed fees at ₹1,51,000 per client per family per year.
Both charges are far below that, and even the two together come to ₹34,000.
The word all inclusive suggests tax is included, but the site does not spell it out.
Ask for the GST to be shown on the invoice.
What the Fee Does Not Say
The site does not state how long the first engagement runs, how long the plan stays valid or how much support the renewal includes.
A fee is easier to judge when you know the period and the support it covers.
Ask for the engagement period, the number of meetings and the response time in writing.
Fixed Fee and the Commission Claim
A fixed fee means you pay her and not the products she recommends.
Under SEBI rules, an investment adviser takes a fee from the client and does not take commissions on products.
You can test the claim by asking one question.
Ask her to confirm in writing that she earns nothing from any fund, insurer or platform you end up using.
Before You Pay
Take these four steps first, since each costs nothing.
- Ask for the fee, the tax and the period in writing.
- Ask what the renewal includes and when it is due.
- Ask for the refund terms if you stop midway.
- Ask for the payment account name and match it to the registered name.
What Do Upasana Mondal’s Complaint Records Show?
The firm publishes a dashboard as of August 2026 and a twelve month trend. We read both and added the totals again.
|
Source |
Pending at start | Received | Resolved | Total pending | Average days to resolve |
|
Directly from investors |
0 | 0 | 0 | 0 | 0 |
| SEBI SCORES | 0 | 1 | 1 | 0 |
1 |
| SMART ODR | 0 | 0 | 0 | 0 |
0 |
The trend runs from September 2025 to August 2026.
|
Period |
Received | Resolved | Pending |
|
September 2025 to April 2026 (eight months) |
0 | 0 | 0 |
|
May 2026 |
1 | 0 | 1 |
| June 2026 | 0 | 1 |
0 |
| July and August 2026 | 0 | 0 |
0 |
| Total across twelve months | 1 | 1 |
0 |
The sums match, one received, one resolved and none pending.
The One Complaint
The complaint came in during May 2026 and was resolved in June 2026.
The dashboard shows it as received through SCORES, with an average resolution time of one day.
The dashboard and the trend look different at first, since the dashboard is dated August and shows the complaint, while the trend places it in May.
We read the dashboard as a running figure and not a single month, and the adviser could confirm.
What is Missing?
The monthly data begins in September 2025, although she has been registered since 2018.
The research found no annual table and no data for the years before September 2025.
That leaves seven years without a published figure on the page we saw. Ask whether earlier years are available.
How Current is the Data
The latest month is August 2026.
SEBI expects advisers to update complaint data by the 7th of each month, so September data should have appeared by 7 October.
The page may have been updated after our research.
Check it again and ask for the latest figures.
How to Read One Complaint?
One closed complaint over twelve months is a small record. The tables do not say what it was about.
A closed status tells you the complaint was closed, and it does not tell you whether the person was satisfied.
Ask for the general subject and outcome.
If you ever need to raise a case, the guide on a SEBI complaint against investment advisor shows how such cases usually run, and it helps to know that before you commit money.
A search of SEBI’s public records found no SEBI order against Upasana Mondal as of 20 October 2026.
That is not a clean certificate, because orders can be published later and our search was limited.
Does Upasana Mondal Disclose Her Terms, Privacy Policy and MITC?
The research did not find terms and conditions, a privacy policy or other investor disclosures on the website, apart from the complaint data and the Investor Charter.
That does not mean none exist, and she may share them on request.
Without them, you cannot see the terms governing the relationship or how your personal information is handled.
A financial plan needs a lot of personal data.
Asked to pay before you have seen the terms, the MITC or a privacy policy?
Our team reviews your payment proof and whatever agreement exists, drafts a written grievance to the adviser, and takes it to the right SEBI channel if the reply falls short. Register with us for a free consultation.
1. The Agreement and MITC
The Most Important Terms and Conditions, called the MITC, were standardised for advisers from February 2025.
They form part of the advisory agreement and cover fees, risks, refunds and scope.
SEBI rules say the agreement must be signed and handed to you before advice is given or fees are charged.
Ask for both documents by email before you pay.
2. Your Data
Financial planning needs income, assets, liabilities and goals. Ask what she holds, how long it is kept and how you can have it deleted.
3. Refunds
Ask for the refund terms in writing before you pay, because the site does not state them.
Does Upasana Mondal Investment Adviser Offer Insurance Planning or Product Recommendations?
Insurance planning is among the services listed.
Investment advisers are registered by SEBI, while insurance is overseen by a different regulator.
As far as we know, selling insurance products needs a separate licence.
The website says she earns no commissions, so ask her to confirm that in writing, and to say whether the insurance work is a needs assessment or a product recommendation.
Upasana Mondal Investment Adviser Reviews
The research for this blog did not include client reviews.
We have not described any, and a missing review should not be read as a good or bad sign.
Look for dated reviews on more than one platform.
Any review you read is an individual opinion that we have not verified, and the adviser may dispute it.
What Should You Ask Upasana Mondal Investment Adviser Before Paying?
The gaps above can be turned into a short list.
Send these by email so you have a written reply, and wait for the answers before any money moves.
1. What does the ₹22,000 cover?
Ask for the engagement period, the number of sessions, the plan’s validity and what the renewal includes.
2. Is GST included?
Ask for the tax to be shown separately on the invoice.
3. Where is the earlier complaint data?
Ask for figures before September 2025 and for the September 2026 update.
4. Can I have the agreement and MITC now?
Ask for both documents before payment, and keep the email as proof of when they arrived.
5. How are disputes settled?
Ask whether the agreement sends disputes to arbitration. Reading about arbitration in share market cases first helps you judge what such a clause would mean for you.
How Can You Contact Upasana Mondal Investment Adviser or File a Grievance?
The listing shows a Yahoo email address and names her as the contact person.
The research does not list a separate grievance officer, which is typical for an individual adviser.
Write to that email so you have a trail. State your name, payment reference, the issue and the outcome you want in a reasonable time.
If she does not reply or you disagree with the answer, the regulator’s online system is the usual next step.
The page on the SCORES SEBI complaint route covers what to attach and how a case moves after you file.
Keep every reply you get on that system, since they matter if the case has to go further.
Her dashboard also lists SMART ODR as a source.
For a payment disagreement that stays open, the SMART ODR portal brings in a neutral conciliator to go through your papers with you, so keep receipts and replies together.
Disclaimer
This blog is based on the adviser’s published disclosures and publicly available SEBI records as of 20 October 2026. It does not allege wrongdoing, and the adviser is welcome to share her side. We could not independently confirm her credentials, her earlier work history, the scope behind her fees, how insurance planning is licensed, the subject of the reported complaint, or the content of any agreement beyond what the research showed.
Conclusion
Upasana Mondal holds a SEBI registration, publishes a clear fixed fee and reports one complaint, resolved.
The harder part is that the scope behind the fee is thin, the complaint history starts only in September 2025 and the website shows no terms or privacy policy.
Before you pay, ask for the engagement period, the GST, the agreement and the MITC. Keep every reply in writing.
Check the registration and the credentials yourself, and match the payment account to the registered name.
If she answers openly and quickly, you have a better basis to decide.
If a dispute arises later, write to the adviser first and then use the escalation routes in order.
Keep your receipts, emails and screenshots in one folder.
Report. Recover. Stay Fraud Free.
Frequently Asked Questions
The research shows her as an individual investment adviser under INA200011684, valid from 12 September 2018 and listed as perpetual. Confirm the details on SEBI's website and match her name on any payment page.
The website lists a comprehensive financial plan at ₹22,000, described as all inclusive, and a renewal at ₹12,000. Ask for the engagement period, the GST and the refund terms in writing.
The twelve month trend to August 2026 shows one complaint, received in May 2026 and resolved in June 2026, with none pending. Earlier years are not shown on the page we saw.
Her website says she is an independent fixed fee adviser who earns no commissions on financial products. Ask her to confirm that in writing, including for insurance.
Write to the adviser first and keep the reply. If it falls short, a complaint can go through SEBI's online system or the dispute resolution portal, and our guides cover those routes.

 Add us as a preferred source on Google »